S&P Global Ratings cut its outlook on the Meta credit rating to negative on Friday, warning that surging artificial intelligence capital spending and negative free cash flow threaten the company’s balance sheet. The credit agency kept Meta’s rating at AA- but cautioned that rising debt levels could prompt a formal downgrade within two years.
Key points
- S&P revised Meta’s AA- rating outlook from stable to negative following a third-quarter free cash outflow of $2.12 billion.
- Meta raised its 2026 capital expenditure target to as high as $145 billion to fund data centres and artificial intelligence hardware.
- Credit analysts warned that Meta lacks an external cloud business to rent computing power, making near-term cost recovery harder than for its peers.
- Meta pushed back against the assessment and has begun raising $95 billion through share sales to help finance its infrastructure plans.
Why S&P changed the outlook
S&P Global Ratings took the step toward a potential downgrade after assessing Meta’s rising financial commitments. The agency affirmed Meta’s AA- long-term issuer credit rating, which sits four steps below the maximum AAA grade and comfortably above speculative debt. However, shifting the outlook from stable to negative signals that credit analysts see growing structural risks over the next 12 to 24 months.
A central factor in the decision was Meta’s debt relative to earnings. S&P projected that Meta’s ratio of debt to earnings before interest, tax, depreciation, and amortisation will exceed 1.0x by 2027. That represents a sharp jump from roughly 0.1x recorded last year. The agency stated that exceeding that threshold would breach the parameters required to maintain its AA- assessment.
The agency also questioned whether Meta can match the commercial pace of rivals in monetising its technical investments. S&P stated that it remains unclear when new revenue streams will generate material financial contributions that exceed the rising costs of infrastructure over the coming years.
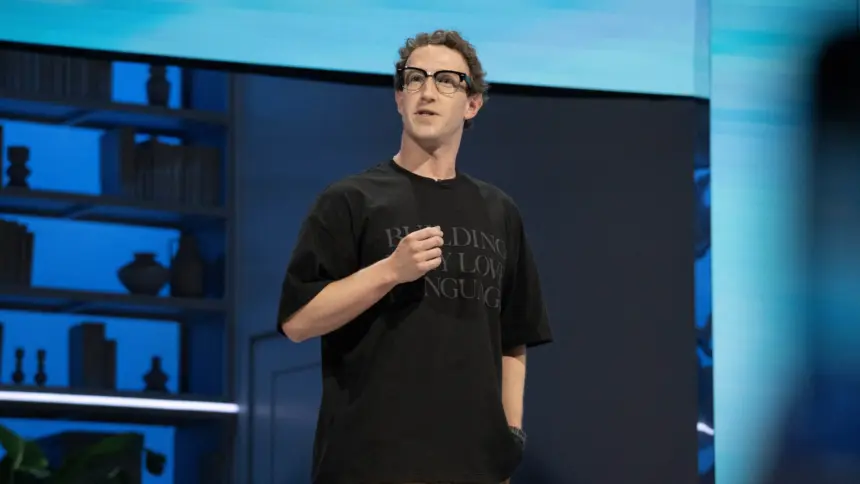
Meta management firmly rejected the downgrade warning. “We respectfully disagree with S&P’s assertion about Meta’s AI monetization capabilities,” said Meta spokesperson Kamran Mumtaz. “We see significant product and business opportunities ahead of us, supporting our very strong credit profile,” he said.
Cash burn inside Meta’s AI push
The rating action followed Meta’s third-quarter financial results, which showed the business running at a cash deficit for the first time. The company recorded negative free cash flow of $2.12 billion during the period. Operating cash receipts failed to keep pace with rapid infrastructure investments across its server farms and computing clusters.
Meta raised its guidance for full-year 2026 capital expenditure to between $135 billion and $145 billion. Chief executive Mark Zuckerberg has told staff and investors that building foundational intelligence systems requires immense processing capacity. He previously acknowledged that the company committed $200 billion to artificial intelligence development without an absolute guarantee of commercial success.
Product costs are already visible in customer software. Meta recently launched Muse, a standalone personal artificial intelligence agent. Running the system requires extensive ongoing compute resources, placing direct demands on hardware capacity without providing an immediate direct fee from users.
To support that balance sheet pressure, Meta announced plans on Monday to raise up to $95 billion. The financing structure includes an initial $35 billion underwritten public equity offering, followed by an additional $60 billion through an at-the-market share issuance facility. Those moves occur alongside $825 billion in total operational and capital commitments already lined up across Meta’s vendor agreements.
Can Meta monetise its models?
Wall Street has grown sceptical about the financial return profile of consumer-facing artificial intelligence. Meta reported a 26 percent increase in digital advertising revenue for the third quarter, proving that its core ad auctions remain healthy. Yet the sheer scale of compute spending has overshadowed that expansion, sending Meta shares down 15 percent across October in their steepest monthly fall in four years.
Unlike Microsoft, Google, and Amazon, Meta does not operate a public cloud infrastructure platform. When competitors purchase processors and build data centres, they can immediately lease that capacity to corporate clients, external software teams, and early-stage companies tracked by services such as venture capital deal tracker StrictlyVC. Cloud revenue can generate immediate cash inflows while those companies develop their internal software.
Meta, by contrast, relies almost entirely on advertising returns to justify its data centres. If open models and internal agents do not produce direct software licensing income or sharp improvements in ad conversion rates, Meta must absorb hardware depreciation and energy bills directly. Corporate debt issuance and regulatory requirements for these large investments are tracked across corporate debt filings monitored through Bloomberg Law, illustrating the financial documentation required as Big Tech shifts from equity funding to large borrowing programmes.
A sector-wide infrastructure bill
Meta is not the only company suffering cash flow strain. Silicon Valley has poured historic sums into data centres, networking gear, and silicon, with capital expenditure plans across Alphabet, Amazon, Meta, and Microsoft topping $740 billion this year alone.
Wall Street reacted sharply to the spending wave. Earlier in the week, Alphabet shares slumped after an AI spending surge drove a $9bn cash drain, marking its second consecutive quarter in the red. Alphabet expects capital spending to reach $205 billion this year, even as user habits shift and publishers react after Google AI cut search referrals to web publishers and altered online commercial traffic patterns.
Amazon faced an even steeper cash drain. Outlays exceeded operating receipts by $42.4 billion across the trailing 12-month period, while annual capital expenditure is set to touch $220 billion. Although Amazon Web Services increased sales by 39 percent, Amazon shares fell 7 percent following its quarterly report.
To bridge the gap between operating profits and construction expenses, tech giants have turned directly to credit markets. Data from S&P Global Market Intelligence shows that Microsoft, Alphabet, Amazon, Meta, and Oracle raised $326 billion in debt during 2026, tripling the borrowing volume recorded in 2025.
What happens next for tech balance sheets?
The rating revision for Meta reflects a broader tightening in credit standards across the technology industry. S&P previously downgraded Oracle after the software maker accumulated heavy debt to fund data centres. Rising power consumption and transmission connections have also created long planning cycles, according to clean power tracking from BloombergNEF.
Equity markets have mirrored the debt market’s anxiety. The tech-heavy Nasdaq fell 2.9 percent on Friday, while hardware suppliers dropped sharply. Nvidia dropped 4 percent, Broadcom lost more than 5 percent, and Qualcomm fell 11 percent as investors questioned how long hyperscalers can sustain current hardware order volumes.
The shifting credit climate could also affect private artificial intelligence developers seeking public listings. Anthropic filed registration documents for an initial public offering this week, but private equity analysts have warned that the startup might fail to secure an investment-grade rating on its own, leaving it dependent on cloud giants to finance computing clusters.
S&P stated that it expects Meta’s capital expenditure growth to begin flattening out in 2028. However, the rating agency said it has grown far less confident that the company will curtail its spending at that point, leaving the door open to a full credit downgrade if cash outflows persist.