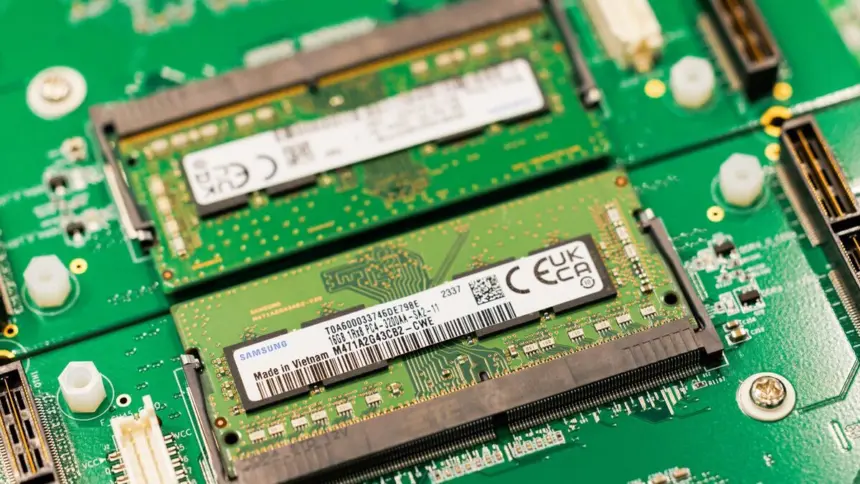
Samsung operating profit reached a record 107.44 trillion won on Thursday, driven by surging data centre demand for high-end artificial intelligence hardware. The South Korean manufacturer became the first technology business to cross the 100 trillion won threshold in a single quarter, lifting total group sales to 195.25 trillion won.
Key points
- Group operating profit grew 783% year on year to 107.44 trillion won during the third quarter of 2026.
- The semiconductor division produced almost the entire profit total, while the smartphone business recorded an operating loss.
- Capital expenditure will climb to 84.4 trillion won this year after the company sold out of high-end memory through 2027.
- Company shares fell 4.1% in Seoul because division earnings slightly missed forecasts and future payout details were postponed.
Memory boom fuels record earnings
Samsung published its third-quarter financial results following a sharp acceleration in data centre expansion worldwide. Group revenue rose 126.88% compared with the same period last year and climbed 13.85% from the preceding quarter. Net profit expanded by 515% to 75.15 trillion won.
The financial return represents the fourth straight quarter in which the company posted record turnover and operating earnings. Hyperscale operators bought dynamic random-access memory and enterprise solid-state drives in heavy volumes, creating tight physical inventories and driving up contract prices across the industry.
Surging memory valuations helped lift Samsung above every other global technology company in quarterly operating income. The results verified preliminary company guidance issued earlier in October, confirming the first time an enterprise in South Korea has generated more than 100 trillion won in operating profit during a three-month window.
Semiconductor unit drives company margins
The Device Solutions unit, which houses Samsung’s silicon manufacturing plants, generated almost the entirety of the company’s operating returns. Operating earnings for the semiconductor unit reached 106.5 trillion won, generated from 147.1 trillion won in division turnover during the three-month period.
The memory division set historical records for both sales and operating profit. Demand rose sharply following the commercial ramp-up of HBM4, the fourth generation of high-bandwidth memory silicon built to supply graphics processing units and specialised accelerators in AI clusters.
Server solid-state drives also contributed to the division’s strong run. Operators of cloud infrastructure purchased large-capacity solid-state storage to handle dataset caching and model weight distribution, allowing Samsung to command higher margins across its flash storage catalogues.
Mobile business slips under component costs
The steep rise in memory component prices created difficulties for other divisions within the company. Higher internal silicon transfer prices hit the consumer electronics operations, where customers showed reluctance to absorb sharp retail price increases.
The Mobile eXperience and Networks division, which sells smartphones and mobile network gear, reported an operating loss of 0.6 trillion won on sales of 37.7 trillion won. Escalating component costs ate away product margins, offsetting the company’s volume shipments across international markets.
Executive management told investors they expect the mobile operation to recover during the final three months of the year. The fourth quarter is traditionally the busiest retail buying period, supported by promotions for the Galaxy S26 line alongside the Galaxy Z Fold8 Ultra and the standard Z Fold8 foldable phone.
The display panel business maintained profitable trading. Samsung Display reported 8 trillion won in turnover and an operating profit of 1.1 trillion won, aided by steady panel deliveries to external smartphone manufacturers and shipments for Samsung’s internal flagship lines.
Market reaction and shareholder returns
Despite the historic earnings totals, Samsung shares fell 4.13% in Seoul on Thursday. The stock had dropped as much as 5% in early trading before reclaiming some ground, having traded up 2% at the opening bell before the details sank in.
Earnings within the chip arm fell roughly 2% short of prevailing analyst consensus estimates. Group operating profit also landed marginally below the 107.66 trillion won projected by LSEG SmartEstimates, which aggregates forecasts from the industry’s most accurate financial analysts.
Investors were also disappointed by the lack of clarity regarding long-term cash returns. The board approved a third-quarter cash dividend of 30 trillion won, which equates to 4,601 won per common and preferred share, but left subsequent distributions open.
The manufacturer indicated it plans to distribute between 55 trillion and 75 trillion won to equity holders across the full year through dividends and share buybacks. The board will postpone deciding the exact execution schedule and cash totals until late January 2027.
Josh Gilbert, lead analyst for APAC at retail brokerage eToro, said market expectations for artificial intelligence hardware providers have climbed to extreme levels.
“Investors have been so spoilt by the AI trade that a record result is now treated as the bare minimum rather than a reason to celebrate,” Gilbert said.
Gilbert said the group’s financial fortunes are now concentrated in one product category. “For all the talk of Samsung being a diversified giant, anyone holding the stock today is really holding a memory maker with a phone business attached,” he said.
Spending surge and supply constraints
To defend its position against global competitors, Samsung intends to expand its annual capital spending by more than 60%. The company expects total capital expenditure to reach 84.4 trillion won, equivalent to around $63 billion.
The investment plan aims to win production share from SK Hynix in South Korea and Micron Technology in the United States. All three memory manufacturers have directed billions of dollars into advanced packaging lines and lithography machinery to support next-generation computing hardware.
Samsung said its fabrication lines have already sold out of high-end memory capacity through the end of 2027. Hyperscalers have secured multi-year supply contracts to ensure their planned data centres receive adequate memory silicon on schedule.
The tightening market mirrors conditions across the semiconductor industry. Domestic competitor SK Hynix reported strong earnings a day earlier and projected that the global memory supply crunch will intensify over the course of 2027 as infrastructure spending expands.
Samsung told analysts it expects broader artificial intelligence capital investments to accelerate in 2027, maintaining upward pricing pressure on high-performance dynamic memory and storage arrays.
Investments in infrastructure and software
Alongside its factory investments, Samsung allocated capital to computing facilities and automated chip engineering systems during the quarter.
Samsung Electronics joined five sister companies to inject $1 billion into KKR-backed Helix Digital Infrastructure. Samsung Electronics provided $500 million of that total, while the five group affiliates contributed the remainder.
The manufacturer also established an engineering partnership with Mistral AI, agreeing to deploy models from the French software developer across its semiconductor plants and design facilities. Samsung led Mistral’s Series D funding round to apply the developer’s tools to semiconductor layout design and factory workflow automation.
Samsung’s board will meet in late January 2027 to finalise the full shareholder return allocation and review capital spending progress for the coming fiscal year.